At a glance · chargeback process
Learn the chargeback workflow from dispute intake to evidence review, response, status tracking and recordkeeping across payment operations.
A chargeback process is a controlled dispute workflow in which a payment is challenged and the relevant parties review evidence under the rules of the payment product, network, bank or provider. Operations teams may handle intake, case creation, evidence collection, response coordination, status updates, reconciliation and record retention. Timelines, evidence categories and decision rights are not universal, so a current provider rulebook must be used for a live case. This guide is a general operations explainer and all examples are fictional.
What happens in a chargeback workflow
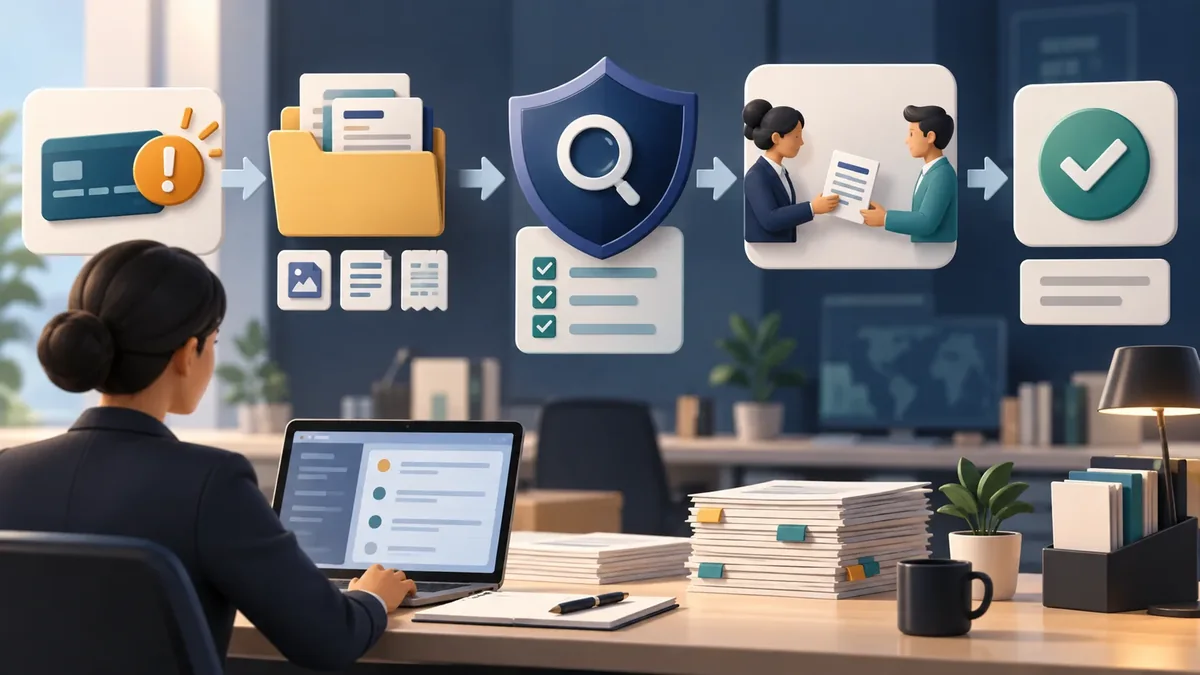
The process often starts with a dispute or notice, followed by validation of the case reference and transaction, collection of relevant records, review against the applicable reason or policy, submission or acceptance of evidence, a decision or further response stage, and final reconciliation. The operations analyst does not decide a customer's rights from a generic checklist. They preserve evidence, follow the authorised workflow and communicate status accurately.
Evidence an analyst may organise
- Transaction reference, date, amount, currency and payment status from authorised systems.
- Order, service, delivery, cancellation, refund or customer-contact records relevant to the case.
- System event history, authentication or approval evidence where the applicable process permits it.
- A clear timeline that distinguishes observed facts from assumptions or explanations.
- Submission status, reviewer decision, next deadline and retained communication history.
A fictional dispute case
A fictional merchant receives a dispute notice for an online service. The associate checks the transaction reference against the order system, confirms the service date, locates the customer-facing cancellation record and records the source and extraction time. One system shows a refund request, while the settlement file still shows the original amount. The associate does not claim that the dispute is invalid. They assemble the timeline, route it to the authorised reviewer and keep the settlement difference open for reconciliation. The case, customer and values are invented.
Try a fictional card dispute evidence packet
Download the five invented source rows for case CB-81, an INR 1,200 online-service dispute. Before reading the answer key, decide whether an order marked completed proves that the service was received, whether a refund request means money was returned, what the analyst can state to a reviewer, and which network or acquirer rule still needs checking. This is a card-dispute exercise, not a UPI failed-transaction example.
Worked answer: preserve uncertainty and the timeline
The notice alleges non-receipt. The order system says completed and a service log records one access event, but the packet does not establish who accessed the service or whether that event satisfies the applicable evidence rule. A refund request is pending and is not proof of a posted refund. The INR 1,200 original settlement belongs in a separate reconciliation trail. The associate should record each source ID, confirm the dispute reason and deadline with the authorised acquirer/provider process, ask for relevant evidence, and hand the file to the designated reviewer. The packet supports no promised outcome for either party.
- Identify the notice, case reference and deadline to verify.
- Separate system status from proof of service delivery.
- Separate a refund request from a posted refund.
- Preserve the original settlement and any later reversal as distinct events.
- Name the authorised reviewer and the source of current evidence rules.
One point per item is a learning aid, not a dispute-decision or hiring assessment. Visa's merchant dispute guidance describes transaction records, evidence and the acquirer channel for Visa card disputes; the applicable network and provider rules must be checked for a real case.
Review Visa's merchant dispute guidance
Controls and customer-safe communication
Chargeback teams should restrict access to sensitive data, use a case reference, preserve evidence, avoid changing source records, and record who prepared and reviewed the response. A status message should say what is known, what is under review and what the customer should do through the official channel. It should not promise a refund, reversal, decision date or outcome unless the authorised system and policy confirm it. Provider-specific deadlines and reason codes must be checked before action.
Quality checks for a case file
A reviewer should be able to understand the case without opening five unrelated systems. The file should show the original notice, transaction identity, relevant timeline, evidence source, response owner, submission status and next action. If a record is unavailable, say so and explain the escalation. Do not manufacture proof from a screenshot or copy a customer statement into a conclusion without checking the underlying source. Clear case notes protect privacy and make later reconciliation easier.
- Use the case reference consistently across systems.
- Distinguish customer communication from verified transaction evidence.
- Record refunds, reversals and settlement differences separately.
- Protect sensitive data and share only the minimum required.
- Review aged cases and recurring dispute causes for process improvement.
Learn the payment reconciliation process
For interview practice, explain how you would keep a dispute file complete without editing evidence to fit a preferred result. A strong answer shows source control, timeline discipline, privacy awareness and escalation. Centaur Careers publishes this article for education; it is not legal, banking, payment-network or customer-specific advice.